

Corporate greenhouse-gas targets have become a central tool for translating global climate goals into company-level action, but research and assessments increasingly question whether existing methods measure meaningful progress. The literature traces the development of science-based targets, identifies weaknesses in emissions accounting and net-zero claims, and points to sectoral, transition-oriented and implementation-focused approaches as possible ways to make corporate climate action more credible, comparable and equitable.
How corporate climate targets developed
Krabbe and colleagues’ 2015 paper established a sectoral decarbonization approach for aligning corporate greenhouse-gas targets with global climate goals. The method is used by accountability initiatives including the Science Based Targets initiative (SBTi) and the Transition Pathway Initiative. It sought to connect a company’s emissions pathway with the reductions required across its sector rather than treating every business as if it faced identical technical and economic conditions.
A 2021 evaluation by Bjørn, Lloyd and Matthews examined seven approaches used to set “science-based” emissions targets. The authors identified strengths and limitations in how those approaches align corporate emissions trajectories with the Paris Agreement. Later work by Rekker and colleagues attempted to measure corporate Paris compliance using a rigorous science-based approach, while a 2025 study argued that corporate emissions benchmarking must balance methodological simplicity with sufficient complexity to remain robust.
Why current targets can miss the mark
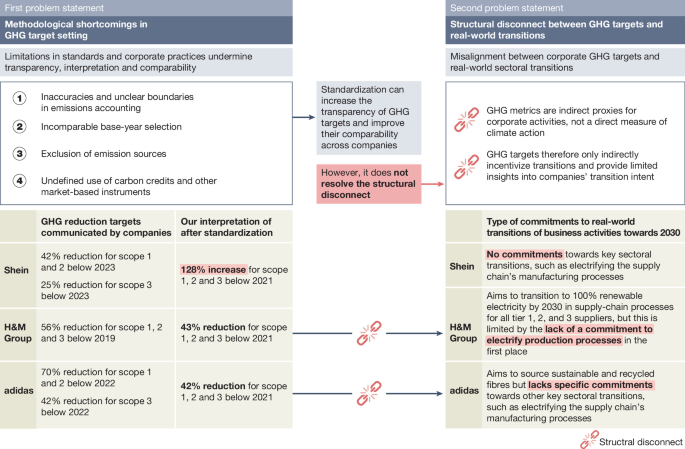
Assessments by the NewClimate Institute have documented weaknesses in the transparency and integrity of corporate emissions-reduction and net-zero claims. Its Corporate Climate Responsibility Monitor reports for 2022, 2023, 2024 and 2025 describe methodological flaws and structural disconnects between corporate targets and actual emissions reductions across multiple sectors.
Several academic papers make related criticisms. Lecocq and Winkler argued in 2024 that the link between mitigation by an individual actor and global temperature targets remains insufficiently robust. Reisinger, Cowie, Geden and Al Khourdajie argued that science-based goals can miss the point when they rely on a narrow set of rules rather than the latest climate science and principles of equity.
Robiou Du Pont and colleagues also criticized the preferential treatment of companies with established independent greenhouse-gas targets. They argued that this can overlook future innovators and fail to recognize companies whose main contribution is to accelerate decarbonization across an entire sector.
The challenge of Scope 3 emissions
Scope 3 emissions—those occurring throughout a company’s value chain—are among the most difficult elements of corporate climate accounting. They may include emissions from suppliers, transport, product use and disposal. The challenge is not only technical: the appropriate accounting method depends on the question a target is intended to answer.
Research and guidance from the SBTi have examined how companies can promote value-chain decarbonization. Its 2023 survey results describe companies’ experiences, while its 2024 Scope 3 discussion paper considers how corporate value chains can be aligned with global climate goals.
Other researchers have questioned whether conventional Scope 3 accounting is fit for every purpose. Ballentine’s 2024 paper asks what question Scope 3 accounting is intended to answer, while Burkov and Gillenwater examine alternative greenhouse-gas accounting frameworks for measuring both inventories and the effects of corporate interventions. Their analysis highlights limitations in current target-setting practices and the need for different ways to evaluate corporate climate action.
Work on corporate emissions accounting has also emphasized the importance of geography. Davis argued in 2025 that understanding the carbon emissions of companies across multiple regions is important, reinforcing the need for accounting systems that can represent complex, multinational supply chains.
From emissions targets to transition action
The source literature points toward targets that measure not only an organization’s reported emissions but also the changes it is making to its products, operations, supply chains and markets. The First Movers Coalition, for example, has developed commitments for hard-to-abate materials and technologies, including steel and aluminium. Its broader commitment framework and 2026 impact overview present demand-side commitments as a mechanism for encouraging early deployment of lower-emissions technologies.
Similar sector initiatives include the Climate Group’s SteelZero and ConcreteZero campaigns. The SBTi has also published land-transport guidance and a second public consultation draft for an automotive-sector net-zero standard. A power-sector net-zero standard was listed as a first consultation draft in 2025.
These approaches shift some attention away from a single company’s emissions trajectory and toward the actions needed to transform an entire sector. They also raise questions about how to credit companies that enable reductions elsewhere, particularly when those effects are not fully captured by conventional corporate inventories.
Standards, accounting and governance
Corporate targets operate within a wider network of voluntary standards, reporting systems and governance initiatives. The SBTi’s Enterprise Net Zero Standard Version 2 was under development in 2026. The GHG Protocol Corporate Standards Suite and Guidance Update Process was also listed in 2026, while the International Organization for Standardization published its 2022 guidance, Net zero guidelines—accelerating the transition to net zero. ISO also listed ISO/CD 14060—Net Zero Coordination Organization in 2026.
Researchers have argued that voluntary action alone may not be enough. Hale and colleagues wrote in 2024 that growing voluntary climate efforts should be converted into formal and enforceable “ground rules” for net zero, combining public regulation with private standards. Becker and colleagues’ 2026 systematic review similarly examined voluntary governance in the context of an urgent, reliable and fair transition to net zero.
Carbon offsets remain another area of concern. ClientEarth’s Briefing: Legal risks of carbon offsets, published in 2022, addresses potential legal risks associated with offset claims. The broader debate concerns whether offsets complement direct emissions reductions or allow companies to make net-zero claims without sufficiently changing their own activities.
Beyond a single net-zero number
A growing research agenda proposes assessing absolute environmental sustainability at different scales rather than relying solely on corporate net-zero dates. Bjørn and colleagues’ 2026 paper, Beyond net-zero climate targets, sets out such an agenda for supporting decision-making at multiple scales.
Other work has explored alternatives to temperature-based targets in public policy. Quagrain, Lynas and Ellis argued in 2026 for replacing temperature limits with clean-energy goals for countries, a proposal that conceptually parallels transition-oriented and implementation-oriented targets for companies. The International Energy Agency’s Net Zero Roadmap: A global pathway to continuing to meet the 1.5°C target provides a global pathway framework, while Riahi and colleagues reported mitigation benchmarks from the 2025 Community Update on Global Emissions Pathways in a 2026 preprint.
Together, these studies suggest that credible corporate climate accountability may require several kinds of evidence: absolute emissions reductions, sector-specific transition milestones, value-chain action, transparent accounting and independent scrutiny. The debate is no longer limited to whether a company has a science-based target, but also whether that target measures the actions and outcomes needed for a fair and effective transition to net zero.
Selected corporate disclosures
Corporate sustainability reports provide examples of how companies describe their climate strategies. The source material includes H&M Group’s Annual & Sustainability Report 2024, Adidas’s Annual report 2024 and SHEIN’s 2024 Sustainability and Social Impact Report. NewClimate Institute’s Evolving corporate climate goals tracks how corporate targets have changed over time.
Source: www.nature.com